 Kyiv, 6 Ivana Dracha St., of. 15

 Your power to win
Anna Vinnychenko conducted a seminar for executives, accountants, and financial directors on the topic “Business Risks within the Framework of Changes to Tax Legislation”
17.11.2020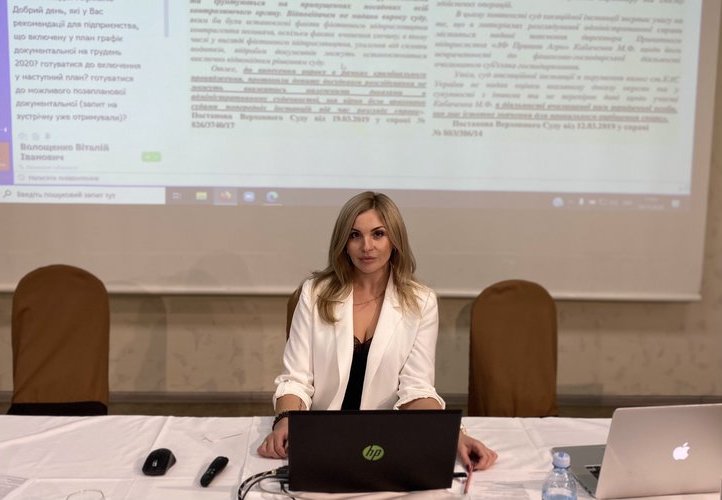
On November 13, 2020, managing partner of WinnerLex law firm Anna Vinnychenko conducted a seminar for executives, accountants, and financial directors on the topic “Business Risks within the Framework of Changes to Tax Legislation,” organized by the Business Club.
The slogan of our law firm is “Business without Legal Barriers,” as we see our mission in providing businesses with maximum legal support.
We provide legal support to businesses not only during legal servicing but also through the organization of professional practical seminars for businesses to minimize potential risks arising from legislative innovations and changes in case law.
The relevance of the 2021 tax innovations and the latest trends in the Supreme Court’s legal positions on tax matters necessitates the consideration of potential risks and “pitfalls” for businesses. The following key issues were addressed during the seminar:
- Business Risks within the Framework of Changes to Tax Legislation:
- How to avoid mistakes that lead to penalties, reassessments, and criminal liability?
- Blocking of tax invoices.
- Challenging the refusal of tax invoice registration. Primary documents. Mutual reconciliation.
- New positions of the Supreme Court. Case law on specific categories of cases.
- Preparation for a Tax Inspection:
- “Risk Factors”: Grounds for conducting a tax inspection.
- Methods to prevent/avoid a tax inspection.
- Rules for quality preparation for a tax inspection.
- Primary documentation audit.
- Thorough verification of business partners.
- Comprehensive protection of documentation and trade secrets. Staff briefing.
- Identifying officers authorized to communicate with the tax inspector.
- Access/Non-Access of the Tax Authority for an Inspection:
- Conditions for allowing tax officials to conduct an inspection.
- List of documents to be presented by inspectors before the inspection begins.
- Deficiencies and discrepancies in these documents to watch for.
- Legal grounds for not allowing tax officials to conduct an inspection.
- Justification for the legality of non-access for inspection.
- Procedures for documenting non-access.
- Administrative seizure of taxpayer assets in case of non-access to the inspection.
- Judicial appeal against the seizure of taxpayer assets.
- Procedure for imposing seizure of funds on taxpayer accounts: Supreme Court’s position.
- Out-of-court seizure of taxpayer funds.
- Compensation for damage caused by the unlawful seizure of taxpayer assets.
- Tax Inspection Procedures.
- Participation in the inspection process. Conditions for exercising taxpayer rights.
- Methods for monitoring compliance with the inspection procedure and responding to illegal actions by tax inspectors.
- Photo and video recording during the inspection.
- Original documents.
- Procedure for providing documents to tax inspectors for review.
- Seizure of original accounting documents.
- Procedure for handing over copies of primary and other documents to tax inspectors: content and form of the inventory of documents handed over.
- Cases in which the provision of documents to a tax inspector may be refused.
- Protection of trade secrets and personal data during the inspection.
- Preventing uncontrolled seizure of documents and extraction of information from electronic systems.
- Consequences of failing to provide tax accounting documents to the tax inspector.
- Form and manner of providing explanations on issues arising during the inspection.
- Tax inspector’s access to the taxpayer’s premises and facilities.
- Recommendations on permissible restriction of the tax inspector’s movement.
- Stocktaking during a tax inspection.
- Suspension of a tax inspection.
- Compensation for damage caused to the taxpayer by unlawful decisions, actions or omissions of the inspectors during the inspection.
- Types of Tax Inspections. Recommendations.
- Desk audit. Place of conduct. Limited scope of the audit. Conditions for the taxpayer’s participation. Lawfulness of a demand to provide additional documents.
- Documentary inspection.
- Types and grounds. Scope of a documentary inspection.
- Scheduled documentary inspection. Notice of the inspection. Time limit. Procedure. Maximum duration of the inspection – consequences of exceeding it.
- Schedule of scheduled documentary inspections. Rules of compilation and criteria for including taxpayers. Taxpayer risk levels. Publication of the annual inspection schedule. Permissible limits for adjusting the schedule: lawfulness of monthly updates.
- Taxpayer’s appeal against inclusion in the inspection schedule.
- Unscheduled documentary inspection. Grounds. Form of notifying the taxpayer of the start of the inspection. Duration of the inspection.
- Prohibition of a repeated unscheduled inspection on issues examined during previous inspections.
- Unscheduled documentary inspection in the case of a cross-check of data on a counterparty.
- Request for documents and written explanations: requirements for form and content.
- Rules for preparing a response to a tax authority’s request.
- How to avoid an unscheduled inspection when preparing a response to a request.
- Cases in which a tax authority’s request may be left unanswered.
- Challenging inspection results due to the unlawfulness of the request that served as the ground for the inspection: case law.
- Off-site documentary inspection.
- Electronic inspection – a method of voluntary audit of the taxpayer’s activities.
- Factual inspection. Scope and grounds. Procedure for informing the taxpayer of the start of the inspection.
- Factual inspection upon a consumer’s complaint.
- An anonymous complaint – a ground for a factual inspection?
- Test purchase.
- Inspection of compliance with the procedure for settlement and cash transactions.
- Control over compliance with labor legislation during a factual inspection: consequences of discovering unregistered employees.
- Formalizing the Results of Tax Inspections:
- Requirements for the format and content of inspection reports. Mandatory requisites of the inspection report.
- Procedures for signing the inspection report.
- Taxpayer’s course of action in case of disagreement with the inspection report findings. Consequences of refusing to sign the inspection report.
- Procedure and timeframe for submitting objections against the inspection report.
- Procedure for considering objections.
- Taxpayer’s rights during the consideration of objections against the inspection report.
- Unscheduled inspection based on objections against the inspection report received by the tax authority.
- Legal status of the inspection report and its relationship to the tax notice-decision.
- Impossibility of challenging the inspection report in court.
- Tax notice-decision (TND) – the basis for the State Tax Service to determine the amount of the taxpayer’s monetary obligation.
- Procedure for adopting and serving a TND. Proving that a TND was not served.
- Appealing the Results of the Inspection:
- Ways to appeal the results of a tax inspection.
- Business Ombudsman: possibility of involving in the review of a taxpayer’s complaint.
- Administrative appeal.
- Procedure and time limits, recommendations on preparing a complaint, procedure and time limit for its consideration.
- Late consideration by the tax authority: automatic satisfaction of the complaint in favor of the taxpayer.
- Judicial appeal.
- Procedure and time limits, jurisdiction.
- Specifics of judicial appeal after the administrative appeal procedure is completed.
- Inexpediency of challenging the order to conduct an inspection once access to the inspection has been granted.
- “Exhaustion” of the order to conduct an inspection after access to the inspection has been granted.
- Procedural violations during the inspection as grounds for cancelling a TND.
- The Role of Criminal Proceedings in Tax Disputes:
- Protection of taxpayer interests in the event of criminal proceedings.
- Decriminalization of fictitious entrepreneurship (Article 205 of the Criminal Code). Its significance and consequences for business. Other legal mechanisms for combating tax abuse.
- The court’s verdict as grounds for concluding that business transactions between the taxpayer and its counterparties were not real.
- Limits on the court’s consideration of a criminal verdict when deciding a tax dispute: current case law.
- Record of the questioning of a counterparty’s director as evidence in a tax dispute.
- The relationship between a fictitious counterparty and the taxpayer’s tax benefit: the Supreme Court’s position.
Anna Vinnychenko and the team of professional attorneys of WinnerLex law firm provide daily legal support to business structures in their interactions and issues with regulatory authorities (tax and customs authorities, Antimonopoly Committee, State Labor Service, State Land Agency) and continuously monitor legislative changes, especially in light of the latest wave of reforms and legal innovations.